From Blueprint to Closing Table.
Design. Real estate. Financing. Branding. Most people assume that's four separate calls. With us, it's one.
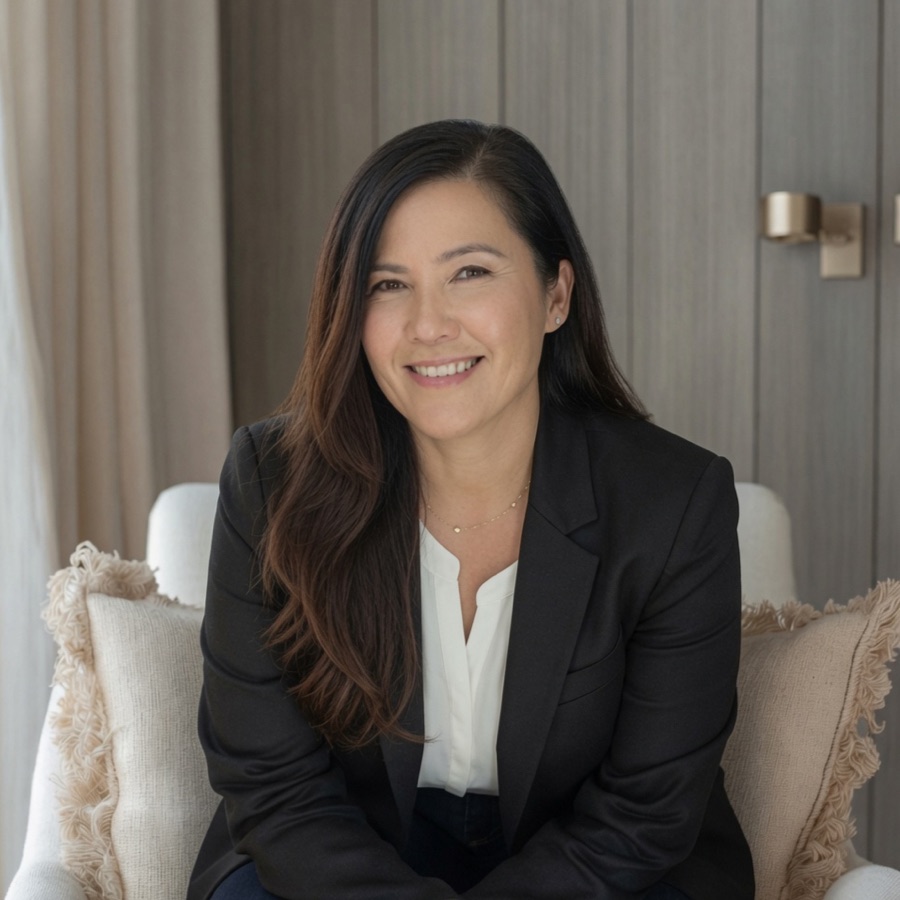
I'm Ariane Bibas, founder and principal of Ariane Bibas. I hold a Master of Architecture from the University of Pennsylvania and have spent more than twenty years guiding clients through high-end residential and commercial renovation projects.
The question I heard most often beyond the design challenges was "Can you help with the financing and real estate, too?" As a licensed mortgage loan officer and a California REALTOR®, I lead our design, real estate and branding teams every day, working alongside licensed architect partners, so your home, and the business behind it, come together under one roof.
We're a full-service firm dedicated to crafting beautifully curated, functional homes, and we go beyond architectural and interior design to handle everything design-related — financing, real estate and branding — for seamless, efficient, turn-key solutions tailored to each client, with a mindful eye on budget and schedule.
Clear numbers. Straight answers. Someone genuinely in your corner. Let's discover your solution together.
- Ariane Bibas
- Mortgage Loan Officer, C2 Financial Corporation · NMLS #2833531
- REALTOR®, Cal State Realty · CA DRE #02225025
- Founder & Principal, Ariane Bibas
Whatever Your Situation, Let's Look at the Options.
Ariane Bibas brings four dedicated teams under one roof: design, real estate, financing and branding. Every part of your home — and your business — moves together, and our goal is for you to leave with a clear next step.

 01 · Design Team
Architectural & Interior Design
Our design team takes your home from first sketch to final install: space planning, renovations, additions and full-service interiors. Architectural plans are prepared with our licensed architect partners.
Design → 02 · Real Estate TeamReal Estate
Our real estate team helps you buy or sell with a designer's eye: what a home could become, and what it will take to get there. Real estate services through Cal State Realty.
Real Estate → 03 · Financing Team
Financing
Our financing team works through C2 Financial, a wholesale mortgage broker with access to a wide network of lenders, comparing programs and pricing for your situation: purchase, refinance, HELOC, construction, jumbo, FHA, VA and more.
Financing → 04 · Branding Team
Branding
Our branding team designs logos, websites and print, from billboards and office signage to trifolds and flyers, for designers, agents, lenders and small businesses, including the website you're on now, plus SEO and AEO so clients find you on Google and in AI answers.
Branding →
From Today to Move-In Day.
Four stops, one firm. Start wherever you are, and we'll carry the rest.
Plan
Space planning, renovations and additions, starting with what you want your home to become and a budget to match.
Architectural & Interior DesignFind
Buy or sell with a designer's eye: what a home could become, and what it will take to get there.
Real EstateFinance
Purchase, refinance, HELOC, construction and renovation loans, compared across programs and pricing for your situation.
FinancingBuild & Move In
Full-service interiors and final install — the finishing layer that makes the house your home.
See the PortfolioNotes on Money, Home & Renovation.
Construction Loans 101: How Building Your Dream Home Gets Financed
Draw schedules, after-renovation value, and what lenders actually look for.
HELOC vs. Cash-Out Refinance: Which Way Should You Tap Your Equity?
When to keep your first mortgage untouched — and when not to.
Renovate or Move? A Designer-Lender's Honest Framework
The question I've answered for design clients for two decades — now with the financing math.
Loan Calculators & Planning Tools.
Run your own numbers — no signup, no sales call. A full set of loan calculators, from monthly payment to rent vs. buy.

Calculators are educational planning tools only, not a loan offer, quote, pre-qualification or pre-approval. All rates are user-adjustable illustrations and no APR is quoted or implied.
Frequently Asked Questions.
Not at all. Design and financing are separate services, and you can use either one on its own. When you finance a renovation with me, my design background simply means I can read your contractor's bid, ask about budgets that look unrealistic, and talk through which improvements may add value.
Yes. I can be your real estate agent and your loan officer on the same purchase, so the search, the offer and the financing all run through one person who knows your numbers. As a REALTOR® with Cal State Realty, I evaluate properties, comps and renovation potential with a designer's eye, and as your loan officer I help you keep each offer aligned with your financing. Where I act in both roles, full disclosure and your written consent always come first.
Often, yes — and California has expanded ADU permitting in recent years. Common ways to finance an ADU include a HELOC (keeps your first mortgage untouched), a cash-out refinance, or a renovation loan sized on your home's estimated after-renovation value. Each has trade-offs. An ADU may add property value and rental income, and as someone who has designed and managed these builds, I can help you pressure-test the budget before we choose the financing.
Instead of lending against what a home is worth today, the lender may size the loan based on what it's expected to be worth after the work — the "after-renovation value." Funds are held back and released in draws as each stage of work is completed and inspected, not handed over all at once.
There are two structures. A construction-to-permanent (one-close) loan automatically converts to your standard mortgage once the build is done — one closing. A construction-only loan is short-term and has to be paid off with a separate mortgage afterward — two closings. There's also a clock: conventional construction-to-permanent loans typically allow up to 12 months to build (18 months maximum), while FHA's 203(k) renovation loan requires work to start within 30 days of closing and finish within 6 months. Program rules vary by lender, so we can compare the structures and timelines for your project.
A HELOC is a second, flexible line of credit on top of your existing mortgage — your first mortgage and its rate stay untouched. A cash-out refinance replaces your whole mortgage with a bigger one and hands you the difference in cash. If your current rate is low, a HELOC leaves it in place; if current rates are below yours, a cash-out refinance may be worth comparing. Which makes sense depends on your situation — we can run both side by side.
There are financing programs designed for this situation — including FHA's 203(h) program and renovation-style financing to rebuild in place. Which pieces actually apply to you depends on your situation, so it's worth a conversation early. See the Rebuilding After a Fire or Disaster guide for an overview.
It depends on every circumstance: the home, the loan program, your credit, your savings, and what else you need that cash to do. There's no single number that fits everyone, and the minimum may or may not suit your situation.
I can look at your whole picture and lay out options you may not know exist, from low-down-payment programs to down payment assistance, and talk through the trade-offs of what to put down versus what to keep in reserve. Book a call and we can review your options together.
It depends on your full situation. Conventional pricing is generally more sensitive to credit scores, and conventional mortgage insurance can typically be removed once you reach certain equity levels (often around 20%). FHA guidelines are generally more flexible on credit and down payment, but FHA mortgage insurance often lasts the life of the loan when the down payment is small, so some borrowers later look at refinancing into conventional once they've built equity (which depends on qualifying at that time). If you're VA-eligible, a VA loan may also be worth comparing. Try the FHA vs. Conventional calculator with your own numbers, or take the Loan Finder to see which programs may be worth comparing.
Pre-qualification is an estimate based on what you tell a lender. Pre-approval means your income, assets, and credit have actually been verified — it can carry more weight with sellers when you make offers. Neither one is a final loan approval.
Much of the timing is in your hands. Once I have your complete documentation — income, assets, credit — I can promptly prepare your file for a lender's pre-approval review, comparing your file across C2's network of wholesale lenders for programs and pricing that may fit. From there, the pace depends on how quickly information comes in, along with lender, appraisal and underwriting timelines.